

Contents:
What is contribution margin?
Contribution margin is sales revenue minus variable costs. It shows how much money remains after paying the costs that rise or fall with a product, service, or project. Typical variable costs include materials, piece-rate labor, delivery, and sales commissions.
The remaining amount contributes to fixed costs such as office rent, management salaries, and software subscriptions. Once fixed costs are covered, the rest contributes to operating profit.
This metric is especially useful in project-based businesses. A company can calculate it for the whole business, for a group of projects, or for one project. The project view makes it easier to see which types of work generate a useful return and which ones mainly increase revenue.
How is contribution margin different from markup?
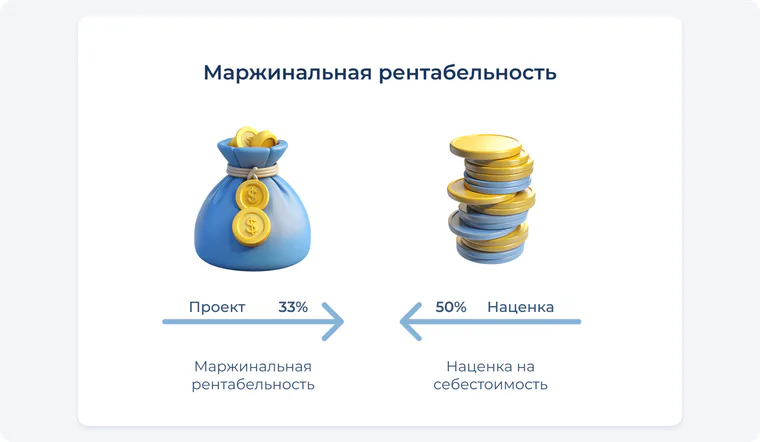
Markup compares a selling price with the underlying cost used to set that price. If a service costs 1,000 monetary units to deliver and the business adds a 50% markup, the selling price becomes 1,500.
Contribution margin measures the amount left after actual variable costs are deducted from actual revenue. It can reveal costs that the original markup did not capture, including extra delivery, outsourced work, or project-specific labor.
| Metric | Calculation | Main use |
|---|---|---|
| Markup | Price minus cost, divided by cost | Setting or reviewing a selling price |
| Contribution margin | Revenue minus variable costs | Measuring the amount available for fixed costs and profit |
| Contribution margin ratio | Contribution margin divided by revenue | Comparing projects of different sizes |
How do you calculate contribution margin?
The formula is straightforward:
Suppose a design-and-build project generates 15,000 monetary units of revenue. Labor, delivery, and other variable project costs total 10,000. The contribution margin is 5,000.
Those 5,000 units are available to cover fixed business costs and then contribute to profit. The calculation does not say that the project produced 5,000 units of net profit, because fixed costs have not yet been deducted.
How do you calculate the contribution margin ratio?
The contribution margin ratio converts the absolute amount into a percentage of revenue:
In the example above, 5,000 divided by 15,000 equals 33%. That means roughly one third of each revenue unit is available for fixed costs and profit.
The ratio helps compare a small project with a large one. A large contract may produce more contribution margin in absolute terms while a smaller contract produces a stronger ratio. Both views matter when time, staff, or equipment are limited.
Why should a business track contribution margin?
Contribution margin helps evaluate projects. It exposes work that generates substantial revenue while leaving too little to cover overhead.
It also supports pricing decisions. A weak margin can point to a price that is too low, variable costs that need attention, or a service mix that consumes scarce resources without producing enough return.
Managers can use the metric to plan capacity. When crews, equipment, or working hours are constrained, contribution margin per limiting resource can provide a clearer comparison than revenue alone.
Finally, it reduces the illusion created by top-line growth. Rising revenue can look impressive even when variable costs are rising at the same pace. Contribution margin shows how much financial capacity the growth actually creates.
How can you track contribution margin across projects?
Start with consistent cost categories. Record project revenue and separate variable project costs from fixed company costs. Apply the same classification rules across projects so the ratios remain comparable.
Review both the contribution margin amount and ratio. The amount shows the total contribution toward overhead and profit, while the ratio shows how efficiently revenue creates that contribution.
101 helps project teams keep current financial records and review project profitability in one workspace. Accurate results still depend on entering revenue and costs consistently and on time.
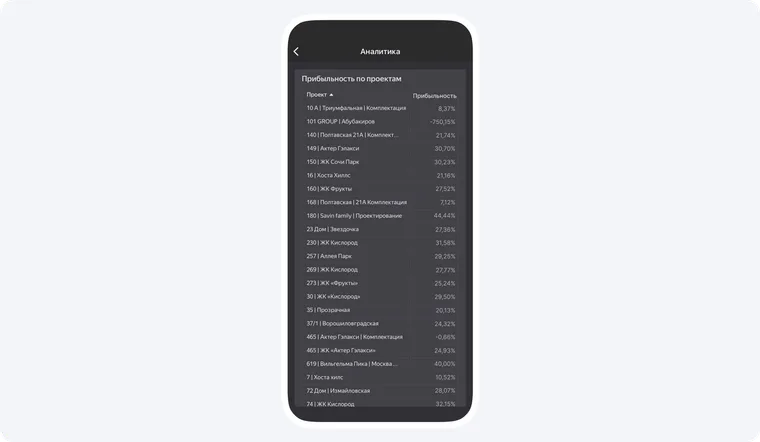
Track the metric over time and investigate changes rather than treating one percentage as a universal target. A useful benchmark depends on the service, cost structure, capacity constraints, and business model.
A short monthly review is enough to turn contribution margin from an accounting term into a practical management tool: compare projects, inspect cost changes, and decide where pricing or delivery needs attention.